|
 |
|
Flats… House Prices and Mortgages
"A lack of supply is still underpinning the rise in house prices with new instructions to estate agents only edging up very gradually," said Rics spokesman Ian Perry.
"Meanwhile, despite the problems first-time buyers are continuing to encounter in securing finance, the level of enquiries from potential purchasers is increasing.
"This imbalance between demand and supply suggests that house prices will move higher in the near term," he added.
The report from Rics supports the widespread opinion in the property industry that house prices have been going up since the spring because relatively few people have been putting their homes on the market.
The number of new mortgages granted for house purchase fell slightly in August to 53,000 from 56,000 in July, the Council of Mortgage Lenders (CML) says.
But the CML's figures indicate that sales may have reached a plateau, with first-time buyers still having to put down very large deposits.
The value of total mortgage lending, which includes remortgaging and buy-to-let deals, was down 36% on a year ago.
Boom and bust
The buy-to-let boom and bust epitomises the rise and fall of the housing market in the last decade.
There is a chance that empty city-centre apartment blocks will be the legacy, not just economically but socially and architecturally too.
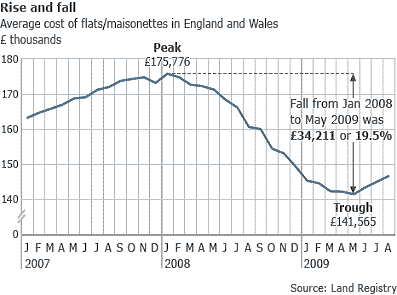 Prices of flats shot up, peaking at an average of £175,776 in January 2008 in England and Wales, according to the Land Registry.
But then prices plunged. By May 2009, the average flat was worth £141,565, when values were falling faster than any other type of property. From peak to trough, the price of a typical flat had fallen by £34,211, or 19.5%. BBC Website news
Replicated
Dated 13 October 2009 – valid for 6 months. AisaProfessional is a trading style of Aisa Direct Ltd, authorised and regulated by
the FSA as Independent Financial Advisers. 1 Fordbrook Business Centre, Pewsey,
SN9 5NU
Notes …
Please note that the opinions expressed in this information must not be
construed as statements of fact – you should carry out your own further research
before coming to a decision and before taking any action.
The views in this letter represent the opinions of Aisa and should
not be construed as a statement of fact. Further advice should be sought before
actioning any investment or tax advice. The Financial Services Authority does
not regulate opinions on the economic outlook, nor does it regulate some forms
of tax advice or comment such as this.
* This
newsletter has been prepared with all possible care to ensure its accuracy. It
is based on our current understanding of legislation and HMRC practice.
* Neither Aisa Direct
Ltd nor any of its employees can accept responsibility for any errors or
omissions. You should seek further professional advice prior to action.
This should not be deemed
as individual advice and you should seek further information particular to your
individual circumstances. For further information, contact
AisaProfessional on (0845) 838 7279. |
 |